One of the less obvious problems facing Kenya’s electric vehicle industry has just been removed. The Energy and Petroleum Regulatory Authority (EPRA) has amended Kenya’s electricity tariff structure to remove the previous 15,000 kWh monthly ceiling that applied to customers using the special e-mobility tariff.
The change was published in the Kenya Gazette on September 18, 2026, and affects electricity supplied and metered by Kenya Power to e-mobility customers at 240 or 415 volts. At first, this might sound like a technical electricity-sector issue that has little to do with someone thinking about buying an electric car. It actually matters quite a lot.
Under the previous arrangement, the dedicated e-mobility tariff covered consumption up to 15,000 kWh per month. That was manageable for a home charger or a relatively small charging operation, but it became a problem for businesses operating electric buses, multiple charging points or battery-swapping stations. The more successful a large charging operation became, the easier it was to hit the ceiling.
EPRA has now changed that structure by replacing the fixed 15,000 kWh ceiling with an Energy Consumption Threshold mechanism. This gives larger e-mobility operators more room to increase electricity consumption without automatically falling outside the special tariff arrangement.
The headline electricity rate itself has not changed. The e-mobility tariff remains KSh16 per kWh, while electricity used during the applicable off-peak period can attract the 50 percent Time-of-Use discount, bringing the energy charge to KSh8 per kWh under the relevant conditions. The weekday off-peak period is generally 10pm to 6am, with longer off-peak periods on Sundays, Saturdays and public holidays.
There is an important distinction here: these are energy charges, not necessarily the final amount appearing on an electricity bill. Other pass-through charges, levies, taxes and adjustments can still apply.
So what does the removal of the ceiling actually change for a Kenyan electric-car owner? For someone charging one EV at home, probably not very much immediately.
A typical private car owner is unlikely to consume anywhere near 15,000 kWh of electricity in a month simply by charging one vehicle. The significance of the change is much greater further up the electric-mobility chain.
Think about an electric bus depot charging dozens of buses every night. Think about a battery-swapping station serving hundreds of electric motorcycles. Think about a commercial charging hub serving private cars, delivery vans, motorcycles and buses.
Those operations can consume large amounts of electricity, and their electricity costs ultimately form part of the cost of operating electric transport. Removing the fixed ceiling therefore makes it easier for charging businesses and commercial fleets to grow without the old tariff limit becoming a barrier. That is particularly relevant as Kenya’s electric mobility market expands.
Electric motorcycles are already becoming increasingly common, while electric buses and commercial fleets are also expanding. EPRA data showed e-mobility electricity consumption rising sharply during 2025, although it still represented a very small share of total electricity consumption.
The change is therefore less about making an individual electric car suddenly cheaper to charge tomorrow morning and more about making the infrastructure around electric vehicles easier to scale. And that could eventually affect private motorists.
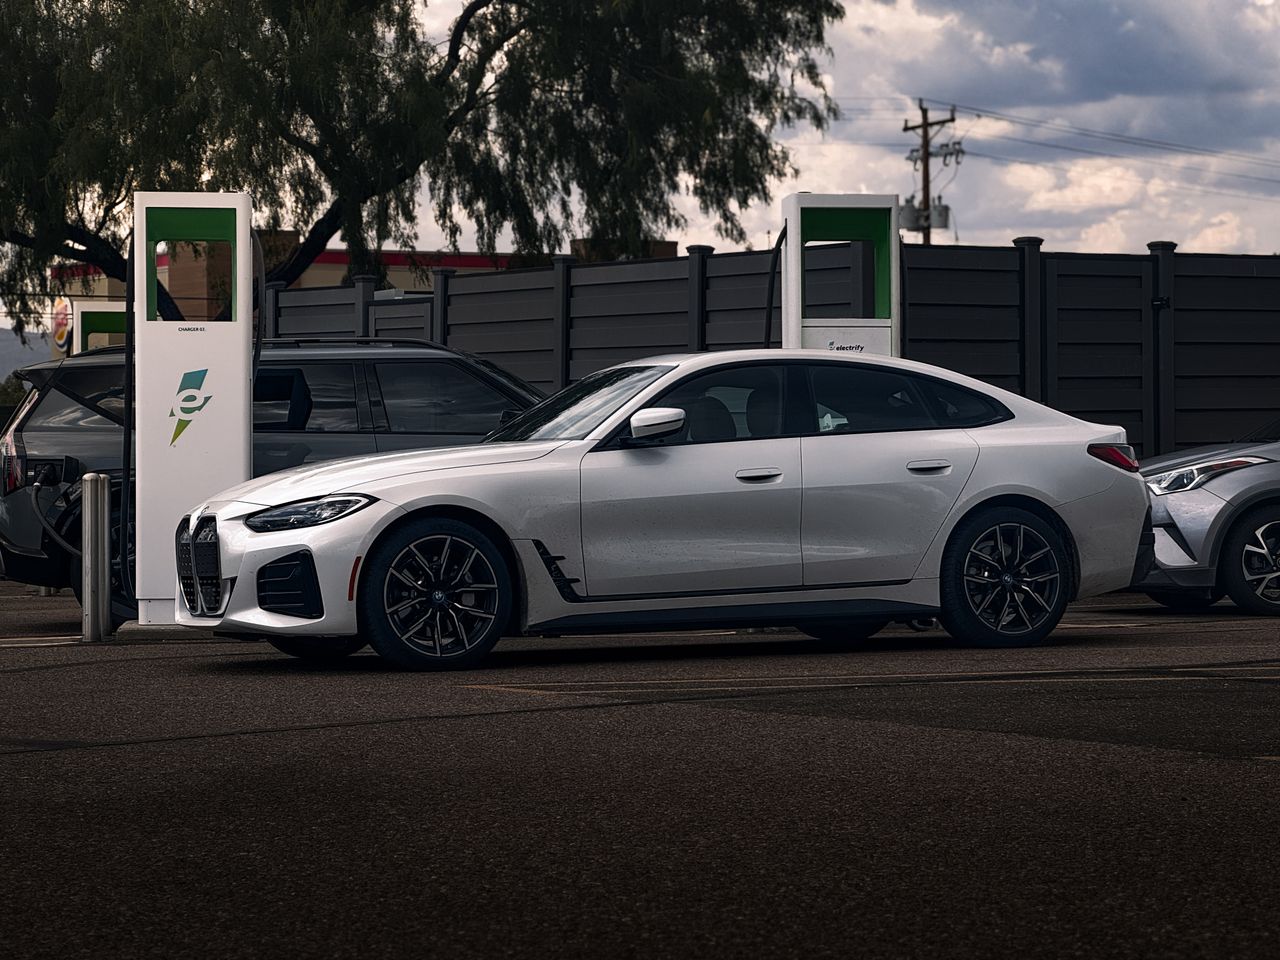
One of the biggest concerns about buying an EV in Kenya has never been simply the price of electricity. It has been whether there will be enough convenient places to charge the car.
A charging company needs to know that it can install more chargers, serve more vehicles and increase electricity consumption without running into an artificial tariff barrier. The same applies to electric-bus operators and battery-swapping businesses. If more businesses can make the economics of charging work, there is a greater incentive to invest in additional charging infrastructure.
There is also a useful lesson here about how Kenya’s EV market is developing. The country is no longer dealing only with the question of whether electric vehicles can work. It is increasingly dealing with the infrastructure and economics needed to support them at scale.
That includes electricity tariffs, charging stations, battery swapping, technical skills, financing and the availability of vehicles. For a private EV owner, the most immediate benefit remains the relatively favourable e-mobility electricity rate, particularly when charging during the designated off-peak periods.
For businesses, the latest EPRA change is potentially much more significant. It means that growing demand for electric transport no longer automatically runs into the old 15,000 kWh ceiling.
And for Kenyan motorists watching the EV market, that is worth paying attention to. Because the electric-car transition will not be determined by the cars alone. It will also depend on whether Kenya can build an electricity and charging system capable of keeping them moving.